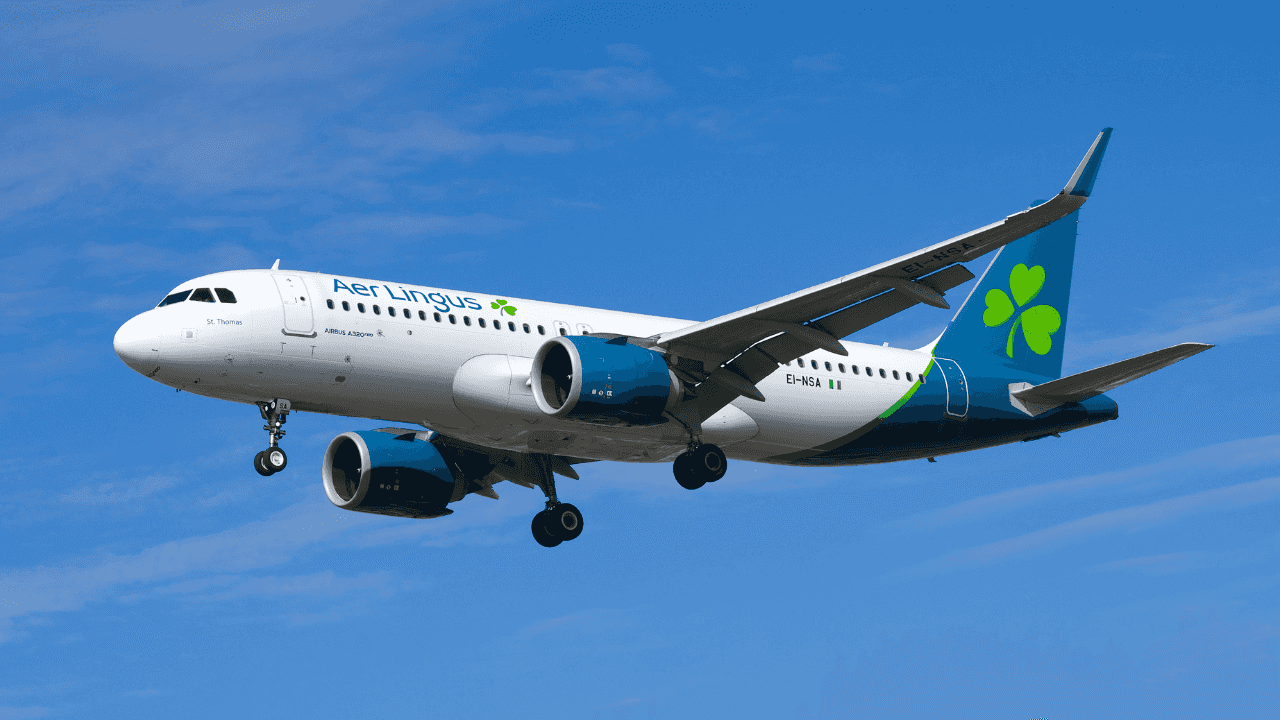
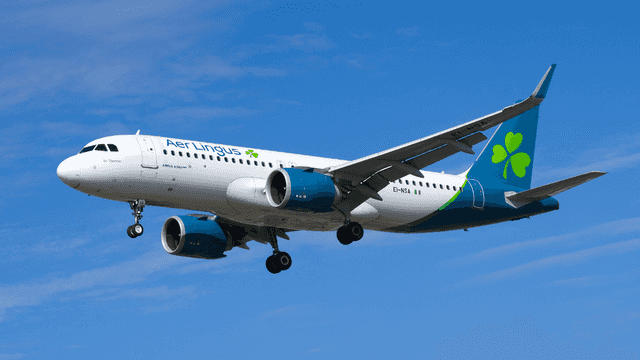
Group ‘take responsibility’ for bomb threat which forced Aer Lingus flight to land at French airbase
News

Share
Published 11:50 23 Aug 2026 BST
Updated 15:50 23 Aug 2026 BST
A notice in the window of Schuh on a busy Dublin street tells you most of what you need to know about how Irish shopping has changed.
It is not advertising a sale. It is advertising Klarna, the option to walk out with what you came in for and settle up later, in instalments. Socks included. In Ireland in 2026, a pair of socks can be bought on credit.
Why it matters: buy now, pay later has moved out of the furniture showroom and into the everyday basket.
Arrangements like these were traditionally limited to larger, big-ticket products.
The popularity of services like Klarna and Humm means the same mechanism now applies to the smallest, most casual purchases, and it has arrived in the middle of a cost-of-living crisis.
Rather than paying the cost of an item upfront, shoppers split the payment into instalments spread over time.
The appeal is obvious. The sticker price does not change, but the amount leaving your account today is a fraction of it.
The services generally make their money in two ways: commission fees charged to the merchant, and late payment penalties charged to the shopper who misses an instalment.
Used deliberately, it can be a convenient way to manage cashflow between paydays. Used casually, it is a way of owing money on socks.
Several major buy now, pay later services only launched operations in Ireland in recent years, and take-up has been quick.
By 2023, nearly one in four people surveyed by the Central Bank said they had used one over the previous year.
The figures indicate the highest rate of use falls among people aged 18 to 34, the cohort most exposed to the squeeze, and the one watching every change to Ireland’s mortgage rules for a route out of renting.
The mechanics are what make it sticky. Because the upfront cost is lower or absent altogether, buy now, pay later can make online shopping seem cheaper or more affordable than it is, even though the item costs exactly the same.
Small, frictionless decisions add up. The bill lands later.
None of that makes instalment credit inherently reckless. Plenty of people use it as a budgeting tool and clear it without ever paying a penny in penalties.
The worry is what happens at the margins, where a missed payment on a low-value purchase turns into a charge that dwarfs the item itself.
The question posed by The Journal’s report is not whether shoppers should be free to spread a payment.
It is whether a service that makes getting into debt more accessible than ever should be promoted this heavily, and this cheerfully, while households are still under real financial pressure.
“Just Klarna it” has become shorthand for a purchase you have not quite decided you can afford. For a generation already stretched, that is a habit worth interrogating before the instalments stack up.
Explore more on these topics:
Group ‘take responsibility’ for bomb threat which forced Aer Lingus flight to land at French airbase
They said they were targeting the ‘feminist regime’. The group behind two of the bomb threats called in to flights across Europe, including one to an Aer Lingus flight today, has been revealed, according to reports. The incidents have caused travel disruption in a number of airports across Europe, with more than 10 flights affected […]
News
6h
Dialysis speech therapy offer from grandfather stuns Dáil
‘I would give anything to hear his little voice’ As Teachta Dála Pearse Doherty revealed that 6,170 children are waiting for treatment, a grandfather’s dialysis speech therapy offer to save his non-verbal grandson’s care has stunned the Dáil. RTÉ reported that the grandfather, 52, offered to end his own dialysis treatment so his three-year-old grandson, […]
News
7h
News
Applications open for brand new two-bed Dublin apartments priced at €1,685 per month
News